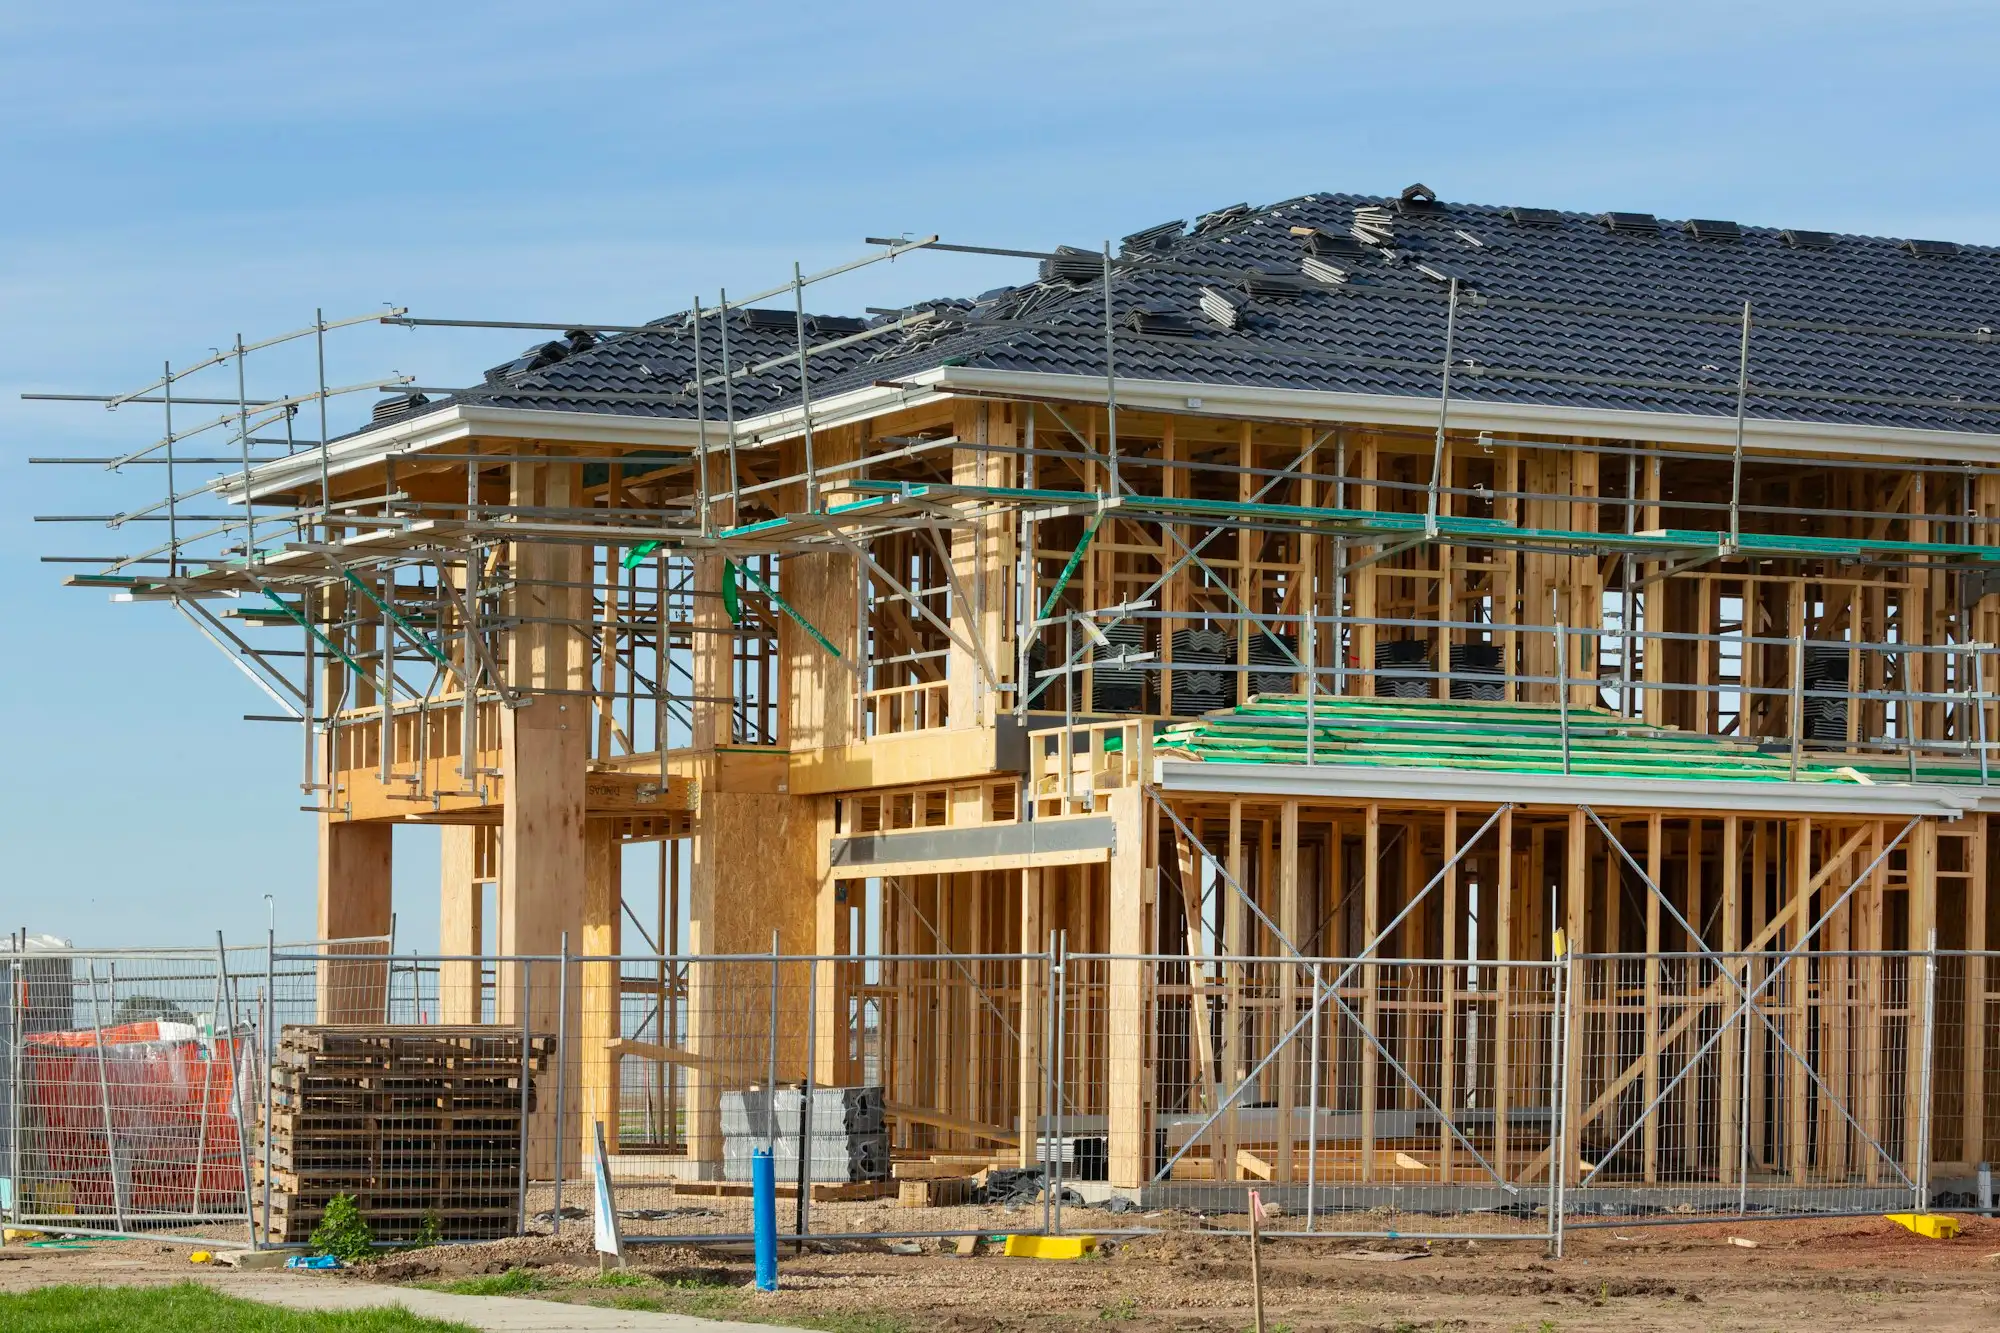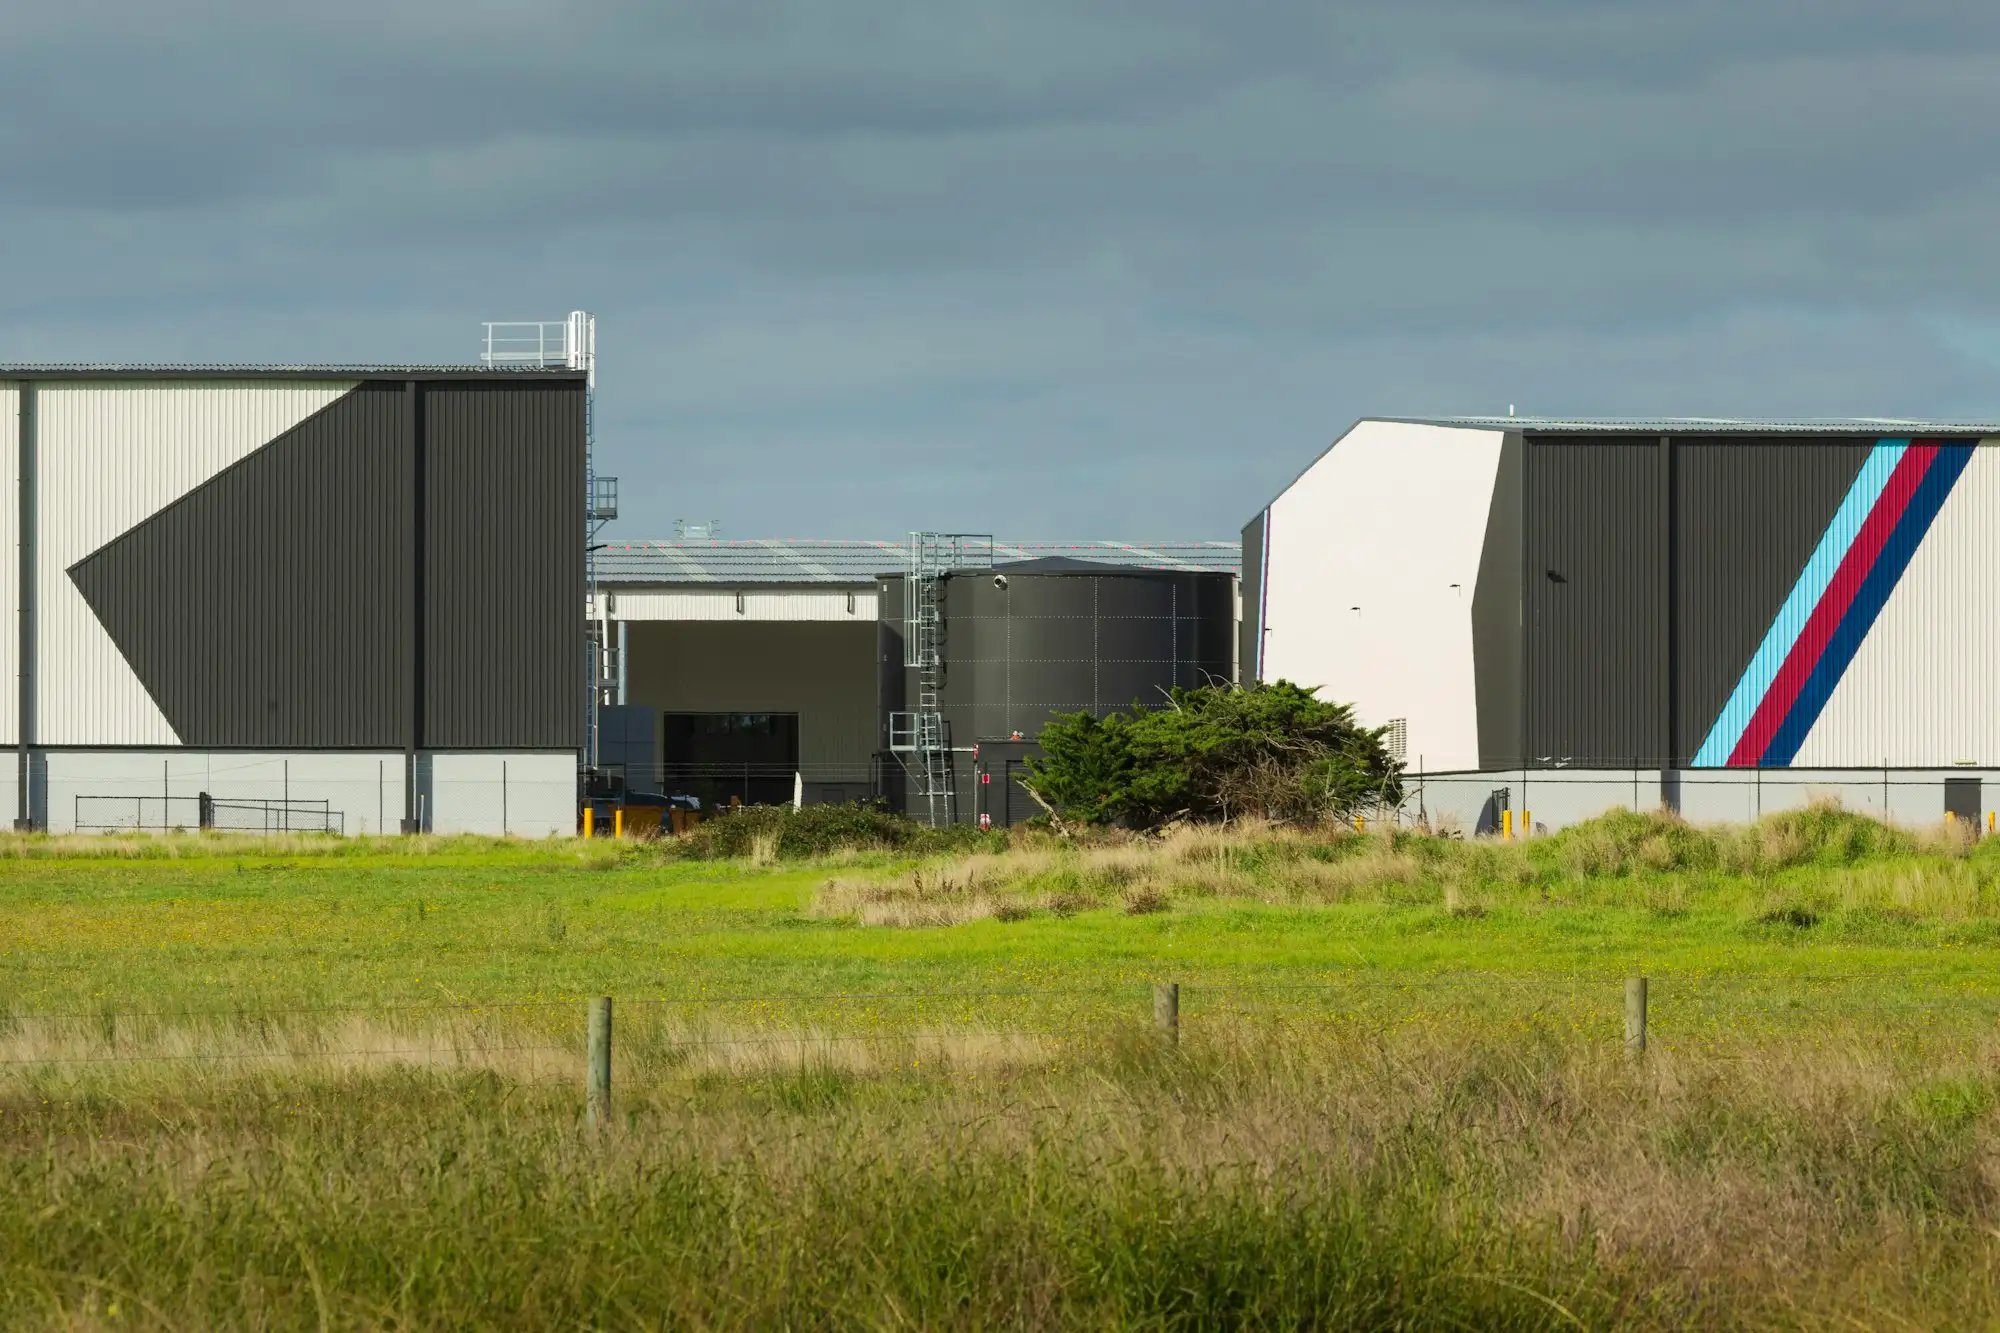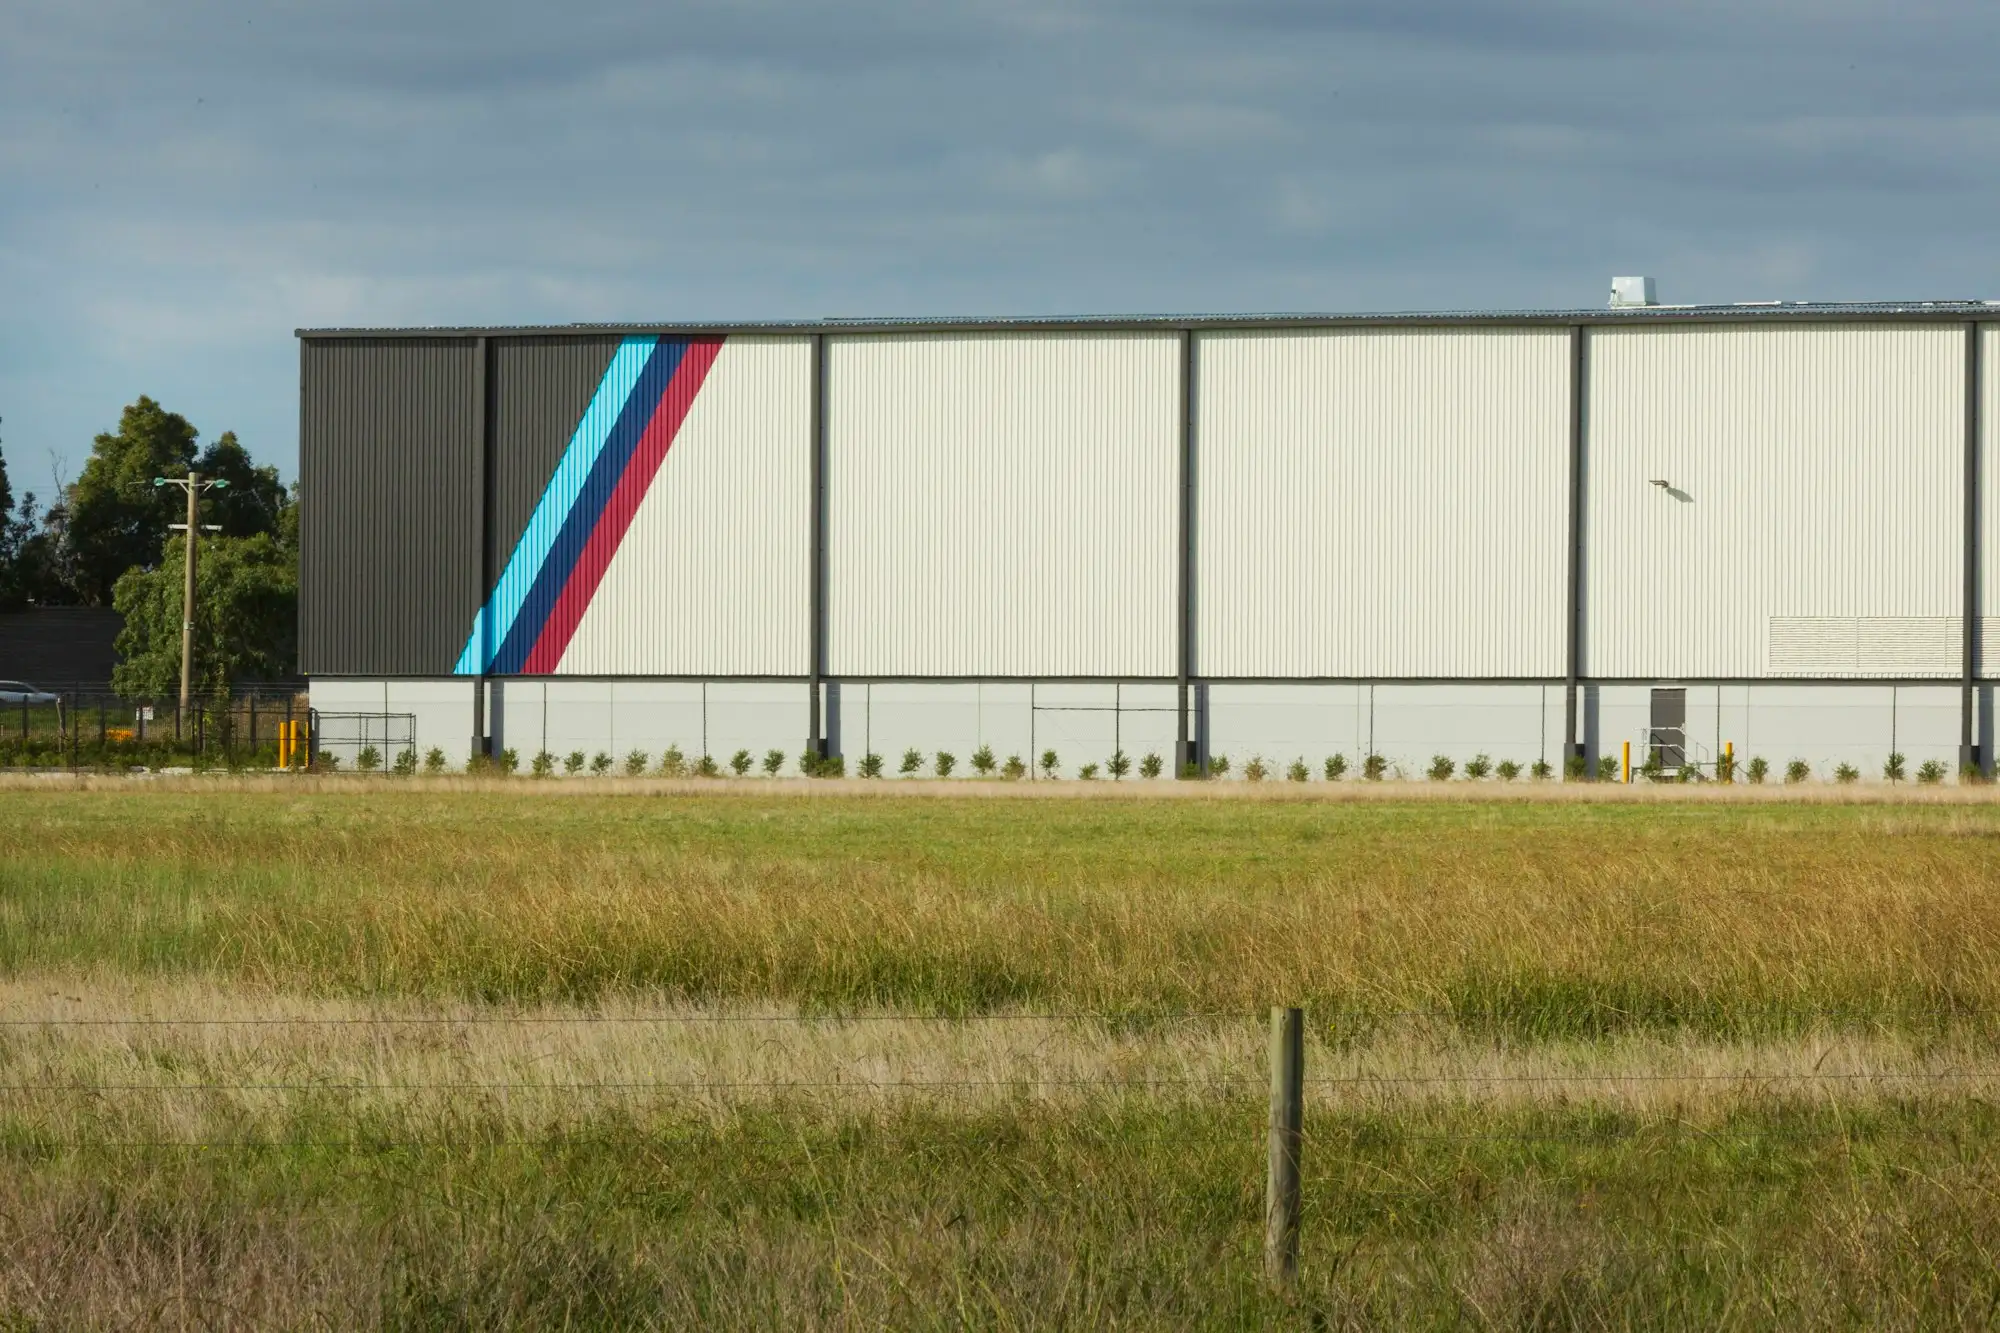
Plenty of tradies reach a point where renting a yard or a factory unit stops making sense. You want your own shed, your own office, maybe a couple of spare units to lease out. Small builders get asked to do the same kind of work for clients. Small commercial construction finance is how those projects get funded fast, without waiting months for a bank credit team.
We keep it small. A shed on a rural block, a single warehouse, a strip of two to four factory units, a small office or showroom. Not towers, not business parks.
What kind of commercial build can be funded?
Typical projects include:
- A tradie building a shed and office on their own industrial block
- A small builder constructing a strata of three or four warehouse units to sell
- A landscaper or earthmover putting up a storage shed and wash bay on rural land
- A small office or medical style fitout building on a commercial lot
- Extending an existing warehouse with a mezzanine and extra bays
If the project is bigger than this, it’s probably not a fit for us.
How is small commercial construction finance secured?
Against real estate you, your company or a guarantor already own, valued as it stands today. That can include:
- Your home or investment property. A common way to fund a first commercial build.
- An existing commercial property. If you already own a factory unit, its equity can fund the next one.
- The land you’re building on. If you own the block outright or with good equity, it can be part of the security at its current value.
The loan is not based on the finished value of the building, and it’s not paid out in progress draws against the development. That’s actually a big advantage for speed: there’s no quantity surveyor signing off each stage before money moves. You get the funds, and you manage the build.
If the property you’re offering is unencumbered, a fast first mortgage is usually the cleanest structure. If you need money to settle on a block before selling something else, look at business bridging loans.
How the money gets spent on a small warehouse build
Every job is different, but a small steel framed or tilt panel warehouse usually runs through these stages:
- Site works. Clearing, cut and fill, stormwater, services connections.
- Slab. Footings, slab and any hardstand for trucks.
- Structure. Steel portal frame or tilt panels, then purlins and bracing.
- Roof and cladding. Roof sheeting, wall cladding, roller doors.
- Services and fitout. Electrical, plumbing, fire services, amenities, office fitout.
- External works. Driveways, car parking, fencing, landscaping.
Map the cost of each stage before you apply. It helps you borrow the right amount and shows the lender you’ve thought it through.
Example: a plumber builds his own warehouse
Hypothetical example only.
A plumbing contractor in Ballarat owns a vacant industrial lot with no debt on it and has approval for a warehouse with an office and mezzanine. His bank wants two years of fresh financials and a long wait for approval, but his steel fabricator has a slot free next month.
He takes a first mortgage over the vacant lot combined with a second mortgage over his home, which together cover the full build cost plus a buffer. The build finishes inside the 12 month term. He moves his business in and refinances to a longer term commercial loan, repaying the short term loan in full. More ideas for trades that build their own premises are on our steel fabricators and welders page.
Planning your exit
Short term construction loans typically run 1 to 12 months, so your exit needs to be clear from day one:
- Refinance to a longer term commercial loan once the building is complete, and ideally leased or occupied.
- Sell units. In a small strata development, sell one or two units to repay the loan and keep the rest.
- Sell another asset. Some borrowers repay from the sale of an investment property or old premises.
Give yourself breathing room. Commercial refinances can take longer than residential ones, and fitouts often run late. Our guide to the exit strategy on a short term loan walks through the options.
Key facts: small commercial construction finance
- Loan size: $20,000 to $5 million
- Security: Existing property equity, including homes, investment property, commercial property or land with equity
- Speed: As little as 24 hours in some cases; typically a few days once valuation and documents are in
- Term: Typically 1 to 12 months
- Financials: Not needed for property secured loans; bad credit considered
- Suits: Small offices, sheds, single warehouses, factory units and small showrooms
Common mistakes on small commercial builds
- Underestimating services. Power upgrades, fire services and stormwater can surprise you.
- Ignoring council conditions. Car parking, landscaping and driveway requirements add real cost.
- No refinance plan. Talk to your broker or accountant about the long term loan before you start.
- Borrowing to the last dollar. Leave a buffer for weather delays and variations.
Start your commercial build sooner
If you’ve got the land, the plans and the trades lined up, don’t let finance be the hold up. Check your options in about 60 seconds, or read more about construction finance for small builds in Australia.