Duplex construction finance is one of the most common requests we get, and for good reason. A duplex or a small row of townhouses is the sweet spot for small builders and investors: big enough to make real money, small enough to manage without a development team. But the finance can be awkward. Banks treat dual occupancies cautiously, want detailed plans and fixed price contracts, and release money slowly. A short term loan secured against equity you already have is often a faster, simpler way to get the project out of the ground.
What kinds of projects does this cover?
We fund small, medium density builds. Typical examples:
- Side by side duplex on a standard or wide block
- Front and back dual occupancy, keeping or replacing the existing house
- Knockdown rebuild duplex on a block you already own
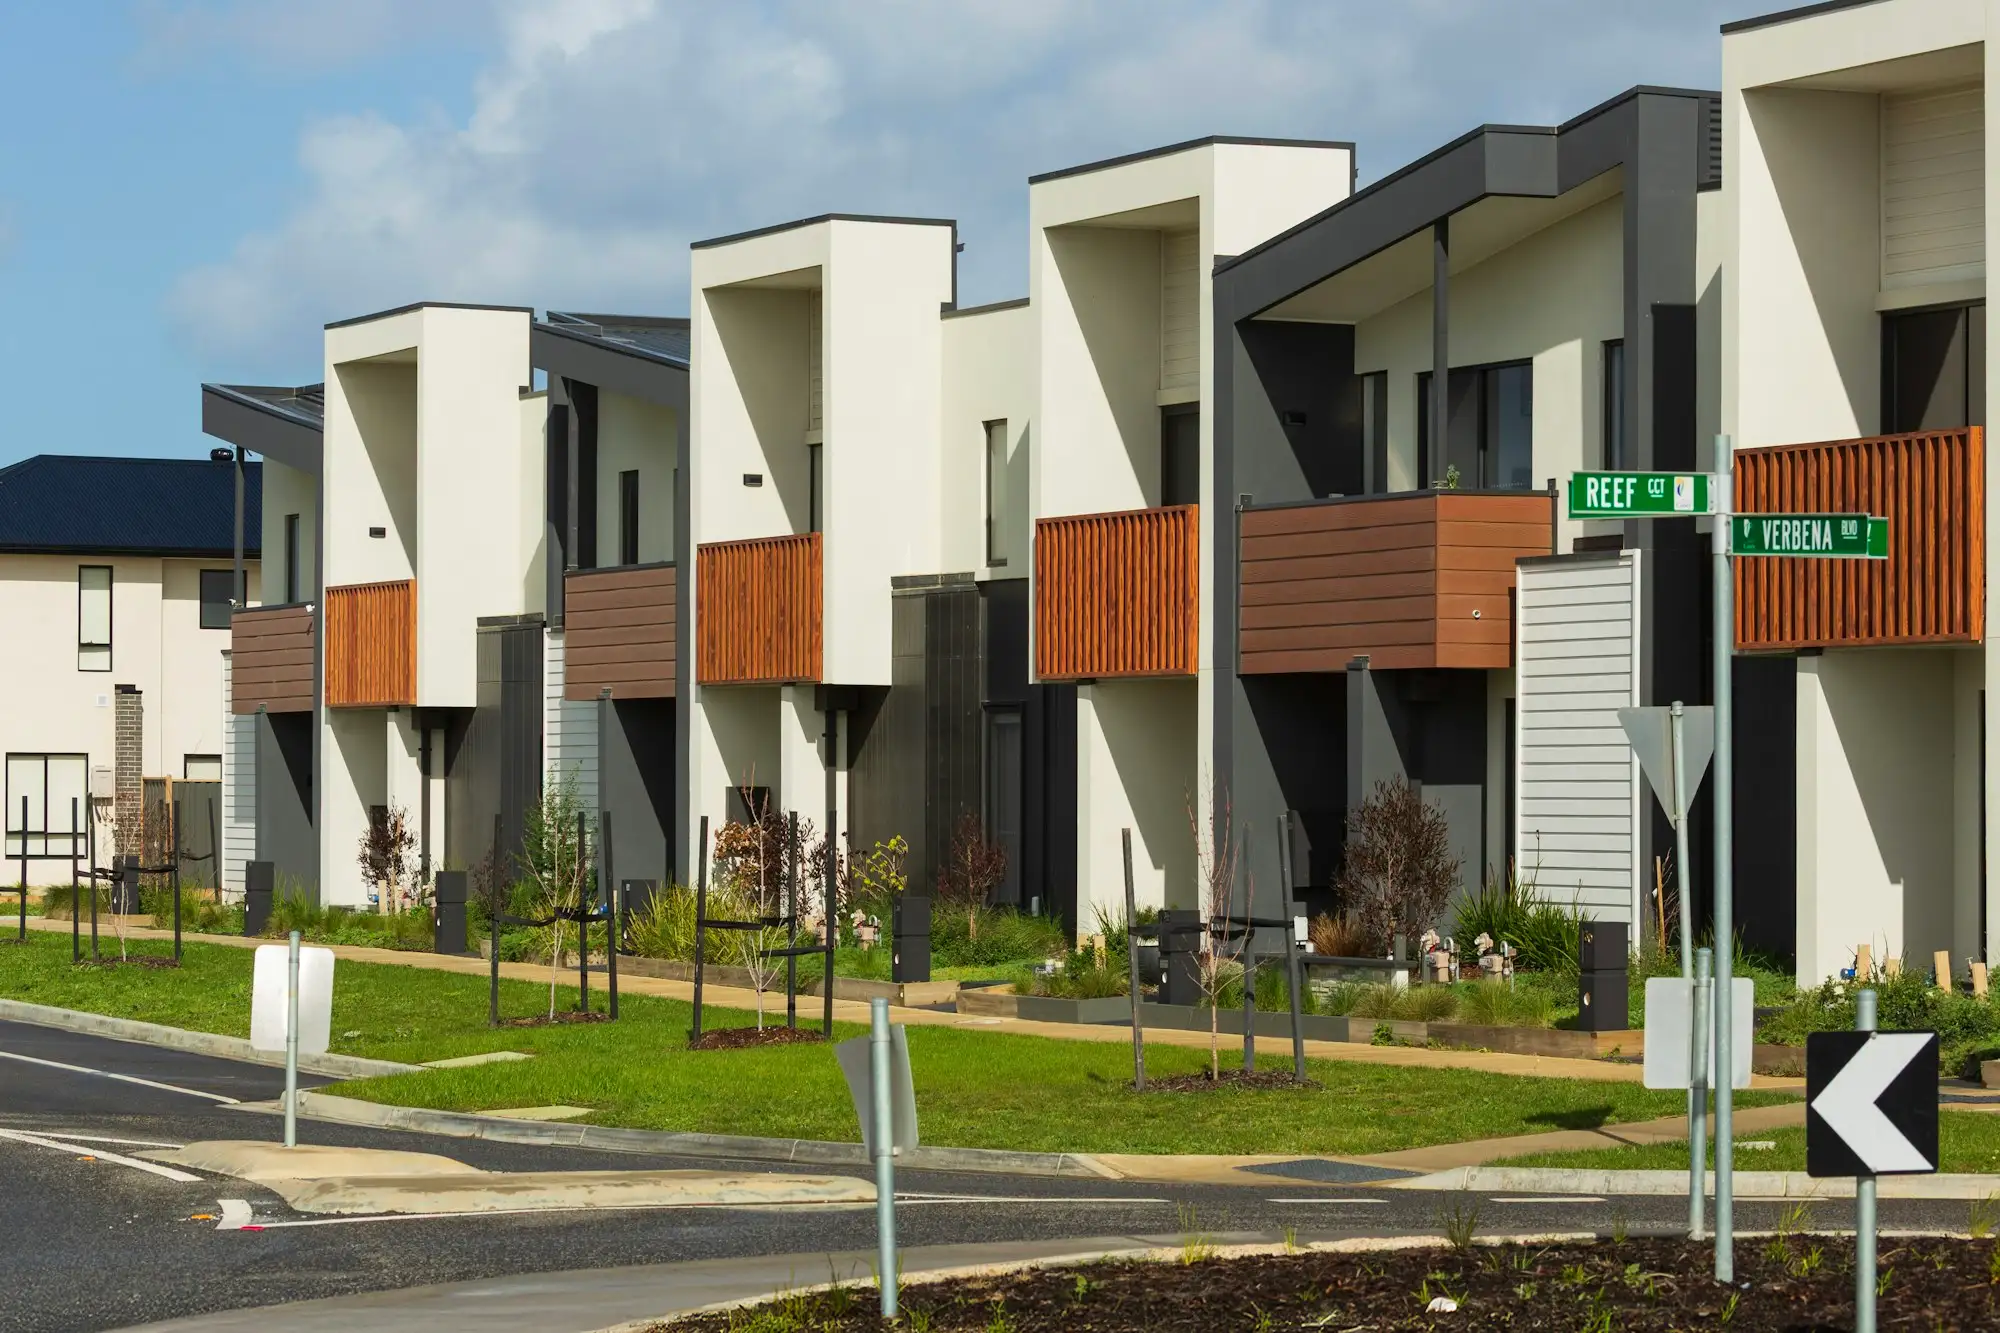
- Three or four townhouses on a larger or corner block
- A granny flat or secondary dwelling added to an investment property
All for business or investment purposes: building to sell, building to hold as rentals, or a mix. We don’t fund large apartment blocks or big multi unit developments.
How is duplex construction finance secured?
The loan is secured against equity in property you or a guarantor already own. That can be:
- The duplex site itself, if it already has good equity
- Your home, often via a fast second mortgage
- An investment property or another block of land
- Commercial property such as a yard or factory
We don’t lend on the “as if complete” value of the finished dwellings, and we don’t release money in progress draws against the build. The funds are settled up front, and you use them as the job needs.
Key facts
- Projects: duplexes, dual occupancies and small townhouse builds of up to four dwellings
- Loan size: $20,000 to $5 million
- Security: existing property equity, including the site if it has enough equity
- Speed: as little as 24 hours in some cases, typically a few days
- Term: typically 1 to 12 months
- Paperwork: no financials or cash flow records
- Credit: bad credit considered
Keep one, sell one: the classic duplex plan
A lot of small builders and investors build a duplex, sell one side and keep the other. The sale repays most or all of the short term loan, and the kept dwelling becomes an investment property with a much smaller loan against it, or none at all.
Example (illustrative only): a builder owns an older house on a wide block in a Brisbane suburb. They knock it down and build a side by side duplex. The build is funded by a second mortgage over their own home, because the block itself only has modest equity after its current loan. When the duplex is finished and titles issue, they sell one side. The sale repays the second mortgage, and they refinance the other side to a long term investment loan.
Timing: titles, practical completion and settlement
With duplexes and townhouses, the build is only part of the timeline. After practical completion, you may still be waiting on:
- Final inspections and occupancy certificates
- Registration of the plan and new titles issuing
- Buyers’ finance and settlement if you’re selling
Each of those can take weeks. If your loan term only covers the build, you can find yourself squeezed right at the finish line. Plan the term to cover the build plus the title and settlement period, with a buffer.
Duplex or townhouse: how the finance changes
A duplex is usually simpler: two dwellings, often a shorter build, and a clear keep one sell one exit.
Three or four townhouses mean a bigger build, more money and usually a longer timeline. It’s common to split the finance: one loan to get the site ready and the frames up, then a refinance or a new loan once the project is further along. For projects that also involve subdividing the land, see small subdivision finance.
Using a builder or building it yourself?
If you’re a registered builder, you’ll often build the duplex through your own business, which keeps margin in house but ties up your crew. If you’re an investor or tradie using a builder, get a fixed price contract where you can and allow for variations. Either way, the finance works the same: secured on existing equity, settled up front.
What to have ready
- The site address and title details
- Details of any other property you’re offering as security, and any loans on it
- Your planning status and approved drawings, if you have them
- Build quotes or a builder’s contract
- Your exit plan: sell one, sell all, or keep and refinance
- Your ABN and business details
Common duplex and townhouse finance mistakes
- Budgeting for the build only. Demolition, service connections, landscaping, driveways and title costs add up.
- Too short a term. Titles and settlements take time. Allow for them.
- Relying on a hopeful sale price. Use recent local sales of similar new dwellings.
- Starting without the full budget covered. A half built duplex is expensive to carry. If a project has stalled, see construction completion loans.
What does it cost?
Every loan is priced on your circumstances, including the security, the loan size, the term and the exit. We find the sharpest rate available for your situation and show you the full cost before you commit.
Ready to build? Check your options in about 60 seconds. It won’t affect your credit score, and a lending specialist will call you back. For the general build side, see our construction loans page.